The next power boom

Electricity demand is a constant. Like Archimedes' Pi, consumption has hardly changed since 2000. In the US, it is around 4,000 TWh, in the EU it is 3,000 TWh and in Switzerland it is around 60 TWh.
Since 2003, we are investing in the power sector with the ENETIA funds. The technological achievements in the field of energy efficiency have kept the demand for electricity in check during this time. This has enabled a remarkably smooth transition from coal power to renewable power. In Germany, the share of renewable energies in the electricity mix has risen from 3% in 2003 to 65% in the first half of 2025. We really wouldn't have thought this would be possible at the time. The seemingly pre-programmed power system crash never occurred. Today, something remarkable is happening in the electricity sector. The constant, i.e. demand, becomes an accelerator.
Prometheus, Hyperion and Stargate
Prometheus is the bringer of fire in Greek mythology. The Prometheus of the electricity industry is Meta's data center by the same name in the state of Ohio. Here, from 2026, computer chips will convert up to 1,000 MW of electricity into AI applications and a lot of heat. This will significantly fuel electricity demand. These systems run around the clock, all year round. The 1,000 MW corresponds to the output of a large nuclear power plant. At Meta, Prometheus is followed by the Hyperion project in Louisiana. Hyperion, something like the creator of light in mythology, is expected to need 5,000 MW of power by 2030 and the whole project is to be developed at the speed of light. Time is pressing. In Texas, too, the Stargate project is reaching for the stars. The list could be continued almost indefinitely. In our model, we assume that a total of 89,000 MW will be needed for AI applications by 2030. This corresponds to almost the entire capacity of the 94 nuclear power plants in the US existing today.
Refrigerators, air conditioners and data centers
Refrigerators and air conditioners were responsible for the last electricity boom of the 50s and 60s. The data centers are playing a major role in the electricity boom that is just beginning. We expect electricity demand in the U.S. to grow by 4-7% p.a. by 2030. A new dimension.
Graphic: Next electricity boom in the USA.
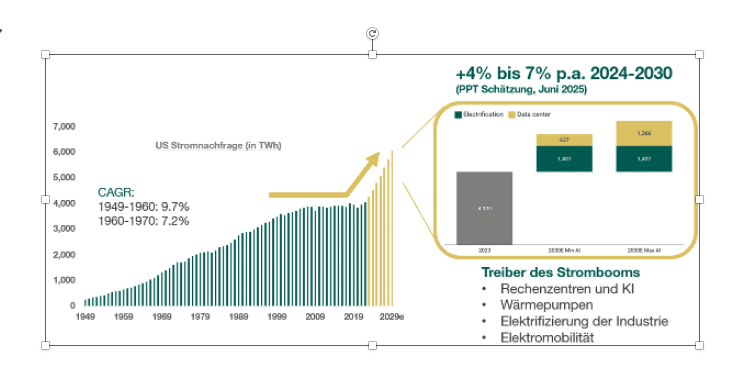
Source: PPT, Clean Grid Initiative and McKinsey. June 2025.
For the first time in 25 years, electricity demand is growing faster than supply. Neither the electricity market nor investors are prepared for this structural shift.
Timelines and costs
Large-scale projects in hydro, nuclear or gas power take a lot of time to complete. A new gas turbine will not be connected to the grid before 2030. New nuclear power plants not before 2035+. Existing gas turbines which are not yet running at full capacity can contribute some to covering the increasing demand. Most of the electricity gap must be covered by renewables.
In the case of electricity, a shortfall is much more serious than in the case of other energy sources. Electricity can not be stored in large quantities.
Wind and solar plants with battery storage systems can be implemented quickly. Most renewable energy subsidies have also survived the One Big Beautiful Bill Act. Against all the "energy-reactionary" zeitgeist. The speed to market is not the only advantage of renewable energies. They are unrivalled in terms of production cost.
On-shore wind power with a 4-hour battery storage system can be realized at 25-50 USD/MWh. Solar is slightly more expensive with the same amount of storage storage: 35 to 75 USD/MWh. A new gas-fired combined-cycle power plant costs 90-115 USD/MWh today! In Iowa or Colorado, new wind turbines run at full load 40% of the time and produce electricity at less than 30 USD/MWh. In combination with storage technology and AI applications in demand management, a reliable power supply can be implemented very cost-effectively.
Graphic: Time to market and cost of different generation technologies.

Source: NextEra Energy, August 2025.
What are the implications?
- Electricity prices will rise significantly. In North America, a doubling of prices is quite possible. The price increase overseas will be faster than in Europe. The demand dynamics are many times stronger. Europe will follow with a delay of 2-3 years. In Switzerland, too, we will feel the jump in power demand from data centers in Volketswil, Rafz or Dielsdorf.
- Renewable energies are underestimated and undervalued by the capital market. Even if people like to talk about nuclear energy again, in the next 5-10 years more than 80% of the new production capacity will come from renewable energies. In 2024, it was 94% in the US. The capital market often values existing renewable energy assets at a discount to construction cost. Growth pipelines are generally ascribed almost zero value. This offers an attractive entry point for investors.
- New market participants with a high willingness to pay. Rising electricity prices always involve political risks. However, today's electricity boom is being paid for by financially strong companies such as Google, Meta or Amazon. Regulators are called upon to take the right steps. If regulated properly, electricity costs for all market participants can be stabilized, if not even reduced.
- Structural growth in the electricity sector. Our ENETIA fund strategies benefit from the electrification dynamics. While the funds have done well, there is still a lot of room left to the upside. It will take some time for market participants to fully price the structural shift in demand into our company share prices.